Introduction – the current view of supply chain challenges
The lesson of the last few years is not simply that supply chain disruption happens more often. It is that disruption now travels through multiple channels at once – trade policy, regional conflict, cyber activity, energy prices, sanctions, logistics capacity, supplier concentration, and market sentiment.
The current supply chain environment is therefore best considered as a system of interacting pressures rather than a sequence of isolated shocks. The International Monetary Fund’s (IMF) April 2026 World Economic Outlook states that, after withstanding higher trade barriers and elevated uncertainty, the global economy now faces a ‘major test’ from war in the Middle East, with global growth projected to slow to 3.1% in 2026 under its limited-conflict assumption. It also notes that commodity prices, inflation expectations, and financial conditions are testing recent resilience.
The World Trade Organization (WTO) paints a similar picture for trade. World merchandise trade grew strongly in 2025, but the 2026 outlook is not predicted to be so positive. Its March 2026 Global Trade Outlook and Statistics says high oil prices related to the Middle East conflict could shave 0.5 percentage points off merchandise trade growth, while prolonged disruption could keep transport and fuel costs elevated and also disrupt key shipping and air routes.
For UK organizations, the news does not come as a surprise. The House of Commons Library noted in April 2026 that the first economic effects of the US/Israeli conflict with Iran were being noticed by UK consumers and businesses, although it did point out that flexible supply chains may cushion price pressures. It also observed that it remains uncertain whether temporary disruption will result in longer-term structural change, such as supplier diversification or rerouting of trade flows.
This creates a degree of complexity for senior management. A supply chain can be technically compliant and diversified ‘enough’, yet it still remains fragile if it depends on a narrow group of shipping lanes, critical materials, cloud providers, contract manufacturers, or logistics partners. The new question is not “can we source this more cheaply?” but “can we continue to serve customers if this route, supplier, jurisdiction, platform, or trade assumption fails?”
What has changed in the last six months?
Firstly, trade policy uncertainty has become a specific operating variable. Descartes’ recently released May Global Shipping Report reported that US container imports fell 5.5% in April 2026 as importers dealt with trade policy uncertainty and geopolitical risk, while Chinese-origin container imports fell 15.3% year-on-year. However, while this might paint a bleak picture, Descartes added that continued resilience remained in underlying demand with April volumes remaining around 19% above pre-pandemic levels.
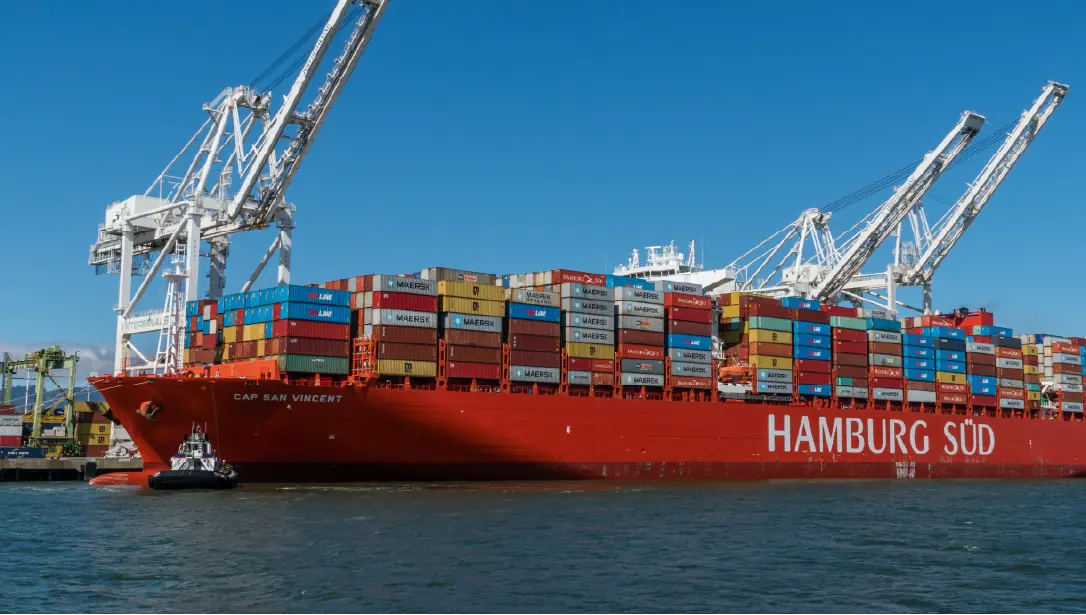
Secondly, regional conflict is now manifesting itself in logistics routing, fuel cost, and demand forecasting. The House of Commons Library reported that shipping through the Strait of Hormuz – which it described as a passage for around 20% of global oil and gas trade – had largely ceased following Iran’s announced closure of the route. This shows that even where organizations might not be directly exposed to a region, they may be exposed to factors such as higher energy prices, longer lead times, freight volatility, or demand changes in affected markets.
Finally, competition in logistics is evolving fast. Amazon announced on 4 May 2026 that “any business can now move, store, and deliver” goods using the same supply chain that supports Amazon.com, extending its freight, distribution, fulfilment, and parcel shipping services to businesses of all types and sizes. While the launch of Amazon Supply Chain Services (ASCS) is not geopolitical in itself, it is important to note because resilience is now partly shaped by who controls logistics infrastructure, data, and fulfilment capacity. It named Procter and Gamble, 3M, Lands’ End, and American Eagle Outfitters among early users. Reuters reported that UPS and FedEx shares fell more than 9% following the announcement, while DHL, GXO, and Maersk were also affected according to subsequent market reporting.
However, the share price story is really a deflection from the case in point. It illustrates a very pronounced industry shift: supply chain resilience is increasingly linked to platform power. Organizations that outsource logistics may gain speed, scale, and data-driven forecasting, but they may also become more dependent on a smaller group of dominant infrastructure providers. For resilience practitioners, that creates a familiar trade-off: efficiency and capability on one side, but concentration risk and substitutability on the other.
Geopolitical forces in the supply chain
To provide a practitioner lens on this – and determine if there are any practitioner blind spots – DRI ran a snap survey in the week of 12 May 2026 asking respondents which geopolitical risk they are currently finding hardest to plan for in their supply chains. Out of the four options available, respondents selected regional conflict at 41%, cyber warfare at 26%, sudden trade tariffs at 22%, and resource nationalism at 9% (data correct as of 15 May 2026).
These figures are revealing and suggest, at least amongst the practitioner community, that the hardest risks are not necessarily those with the highest direct cost, but those with the highest uncertainty, fastest escalation pattern, and weakest organizational control.
Regional conflict – the dominant concern
Regional conflict was the most popular category in the above DRI survey, selected by 41% of respondents. This is not a surprise given the current global situation where supply chain disruption is making headlines globally. Conflict can affect supply chains through several simultaneous routes such as:
- Physical disruption to ports, shipping lanes, airspace, and roads
- Energy price shocks
- Insurance and freight cost increases
- Sanctions and export-control changes
- Reduced regional demand
- Supplier workforce disruption
- Heightened cyber security threat levels.
Birkenstock is a recent example of how conflict can affect both logistics and revenue. Reuters reported that the company recorded a €6 million hit to its EMEA segment after a) it was unable to ship some deliveries into the region and b) it faced muted consumer sentiment linked to war. The company responded by rerouting shipments to stronger-growth regions and reallocating inventory.
The lesson here for both management and practitioners is that conflict scenarios should not be modelled only as supplier failure. They should also be modelled as simultaneous stress across transport, demand, cost, working capital, and communications.
Cyber warfare – a supply chain risk, not just an IT risk
Cyber warfare ranked second in DRI’s snap survey at 26%. This is certainly a reflection on how modern supply chains are becoming increasingly digitally integrated. Freight forwarders, manufacturers, retailers, logistics providers, and financial institutions exchange data continuously – and some with fewer precautionary measures than others. While this creates efficiency, it also creates systemic vulnerability.
A cyber incident at a key logistics provider, port operator, enterprise resource planning platform, supplier portal, or managed service provider can quickly become a major supply chain incident. While senior management may feel assured that cyber security is within the remit of the company’s Chief Information Security Officer (CISO), this is not enough in itself to ensure that supply chains are not compromised. Management needs to go beyond the standard remit of the CISO and ensure that the effects of a cyber attack are translated into supply chain impact terms: which products stop moving, which orders cannot be fulfilled, which customers cannot be served, which regulatory notifications may be triggered, and which manual workarounds are viable.
Sudden trade tariffs – planning for policy volatility
The sudden introduction/change of trade tariffs was selected by 22% of DRI survey respondents. While not physically disrupting a supply chain, tariffs can change the economics of a supply chain. Goods may still move, but margin, price, sourcing logic, and customer demand may all shift.
A recent news story about P&G provides a clear example. Reuters reported in April 2026 that P&G maintained its expectation of a near $400 million hit from tariffs on fiscal 2026 profit, while its currency-neutral gross margin fell by 100 basis points. This extends from being a narrow procurement issue and shows that tariffs can affect pricing power, product mix, working capital, customer relationships, and investor expectations.
Packaging supply chains show the same problem at a smaller scale. Supply Chain Dive reported that consumer goods companies and packaging suppliers were still struggling with tariff volatility and the Middle East conflict. One packaging executive said that “These black swan events keep coming at us. We just don’t have time to prepare.” Another consumer goods manufacturer noted that they had been forced to make drastic changes to sourcing strategies for their packaging after ‘Liberation Day’ tariffs meant previous suppliers were no longer viable.
For senior management, this provides significant implications: tariff risk cannot be solved merely by asking procurement teams to find a domestic substitute at short notice. It requires product design flexibility, contractual agility, customs expertise, scenario modelling, and financial tolerance for short-term margin compression.
Resource nationalism – lower ranking, but the potential for high severity
Resource nationalism was selected by 9% of DRI survey respondents. This may reflect the fact that it feels more sector-specific than conflict, tariffs, or cyber. However, for industries that depend on critical minerals, energy, semiconductors, rare earths, pharmaceuticals, food inputs, or specialist chemicals, the effects can be significant.
Resource nationalism may manifest itself as various factors such as export restrictions, local-content requirements, domestic processing mandates, strategic stockpiling, or preferential access for high-performing and highly valued organizations. The risk is particularly acute when a commodity is both operationally critical and geographically concentrated. It should therefore be assessed not by headline probability alone, but by substitutability, switching time, and the extent to which a resource supports critical operations.
Conclusions
Geopolitical implications to supply chain risk are now part of the operating environment. Regional conflict, cyber warfare, sudden tariff changes, and resource nationalism differ in mechanism, but they share one feature: they can expose hidden dependencies faster than traditional planning cycles can respond.
The DRI snap survey results could be viewed as being instructive for practitioners. Regional conflict is seen as the hardest risk to plan for, but cyber warfare and tariff changes are close behind – both of which cut across functions and jurisdictions. Resource nationalism ranks lower, but for affected sectors it can be a major risk. Senior management should avoid treating these risks as separate agenda items and rather ask how they interact with each other.
For business continuity and operational resilience professionals, this shows that organizations need to have a rigorous understanding of critical dependencies, tested alternatives, contractual protection, response structures, and communications approaches. DRI Professional Practices, for example, can help to provide a credible framework for doing this in a disciplined way.
For senior management, it is important to learn that supply chain resilience is not just a cost of doing business; it is a condition for keeping the business viable when assumptions fail. In the next phase of global trade, the winners will not necessarily be those with the lowest-cost supply chains. They will be those with supply chains that can absorb shock, reconfigure quickly, and continue to serve customers when the most complex geopolitical challenges are thrown upon them.
The author
Rachael Elliott is Director of Global Strategy and Innovation for DRI International. Rachael has particular expertise in the technology side of resilience, and has a keen interest in how artificial intelligence can help to transform the resilience of organizations. Her research has been used in the UK Parliament to help develop government industrial strategy as well as in the BDO High Street Sales Tracker, which Elliott was instrumental in developing and is still the UK’s primary barometer for tracking high street sales performance. She maintains a keen interest in competitive intelligence and investigative research techniques.